Venture Is Not an Asset Class, It Is a Handful of Charts
a16z makes the case for more ‘Big Venture’ using evidence that makes the case against it
a16z’s investor relations team published an essay a few weeks ago arguing that institutional LPs are underexposed to venture—especially to the “best managers,” who can access the best companies and outlier outcomes. Unsurprisingly, the remedy is to increase allocations to the “best” (i.e., brand-name) funds. The piece’s premises are mostly right, but almost every step from those premises to its conclusion is weakly supported.
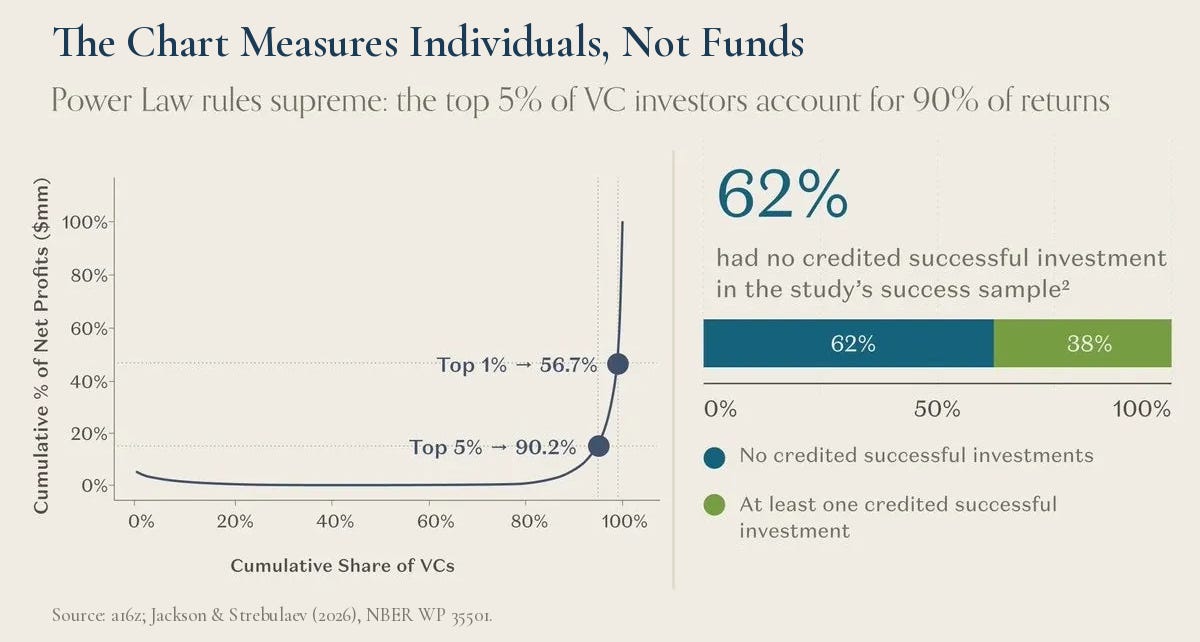
A chart from the essay did much of the work, going semi-viral on LinkedIn and Twitter and generating some… interesting discourse. Its claim: venture isn’t really an asset class at all, just a handful of managers who capture nearly all the returns. It’s a convenient argument. Unfortunately, the data in the chart doesn’t actually support it.
One disclosure first: arguing the countercase serves our interests as an emerging manager, regardless of what we think of a16z’s argument. We trust you to judge both arguments on their merits.
a16z’s argument, compressed: value creation has moved to the private markets and returns are concentrated in a few managers. So the question isn’t whether to allocate more — it’s who you’re allocating it to. Guess who.
To read the full piece, head over to The Verticalist on Substack.