The Vertical Report 2026
Annual state of Vertical AI
2025 was the year Vertical AI moved squarely from hypothesis to reality. After a 2024 defined by AI infrastructure buildout and foundation model wars, capital began flowing decisively toward industry-specific use cases.
The data tells a clear story: across 4,395 VC financings totaling $186B in 2025, vertical startups captured 53% of deal volume and 30% of capital deployed. That share would be even higher if not for a handful of horizontal mega-rounds: OpenAI’s $40B, Anthropic’s $13B, plus several other GPU cloud and foundation model raises. Strip out the 12 deals sized $1B+ and vertical raises took in 51% of 2025 capital.
Some new trends emerged, while others held strong. Healthcare and Financial Services—no surprise—remained the twin pillars of vertical investing, combining for nearly 1,100 deals. 2025’s foremost emergent verticals, however, were Manufacturing & Industrials, Legal, and AEC & Trades. Manufacturing saw a 41% increase in deal count from Q1 to Q4. Legal produced two of the year’s largest rounds, with Clio ($850M) and Filevine ($400M): even if neither of these companies is AI-native, both are quickly becoming AI-powered as competition scales fast. And AEC & Trades saw both early and late stage enthusiasm, anchored by CompanyCam’s $415M round that made it Nebraska’s first unicorn.
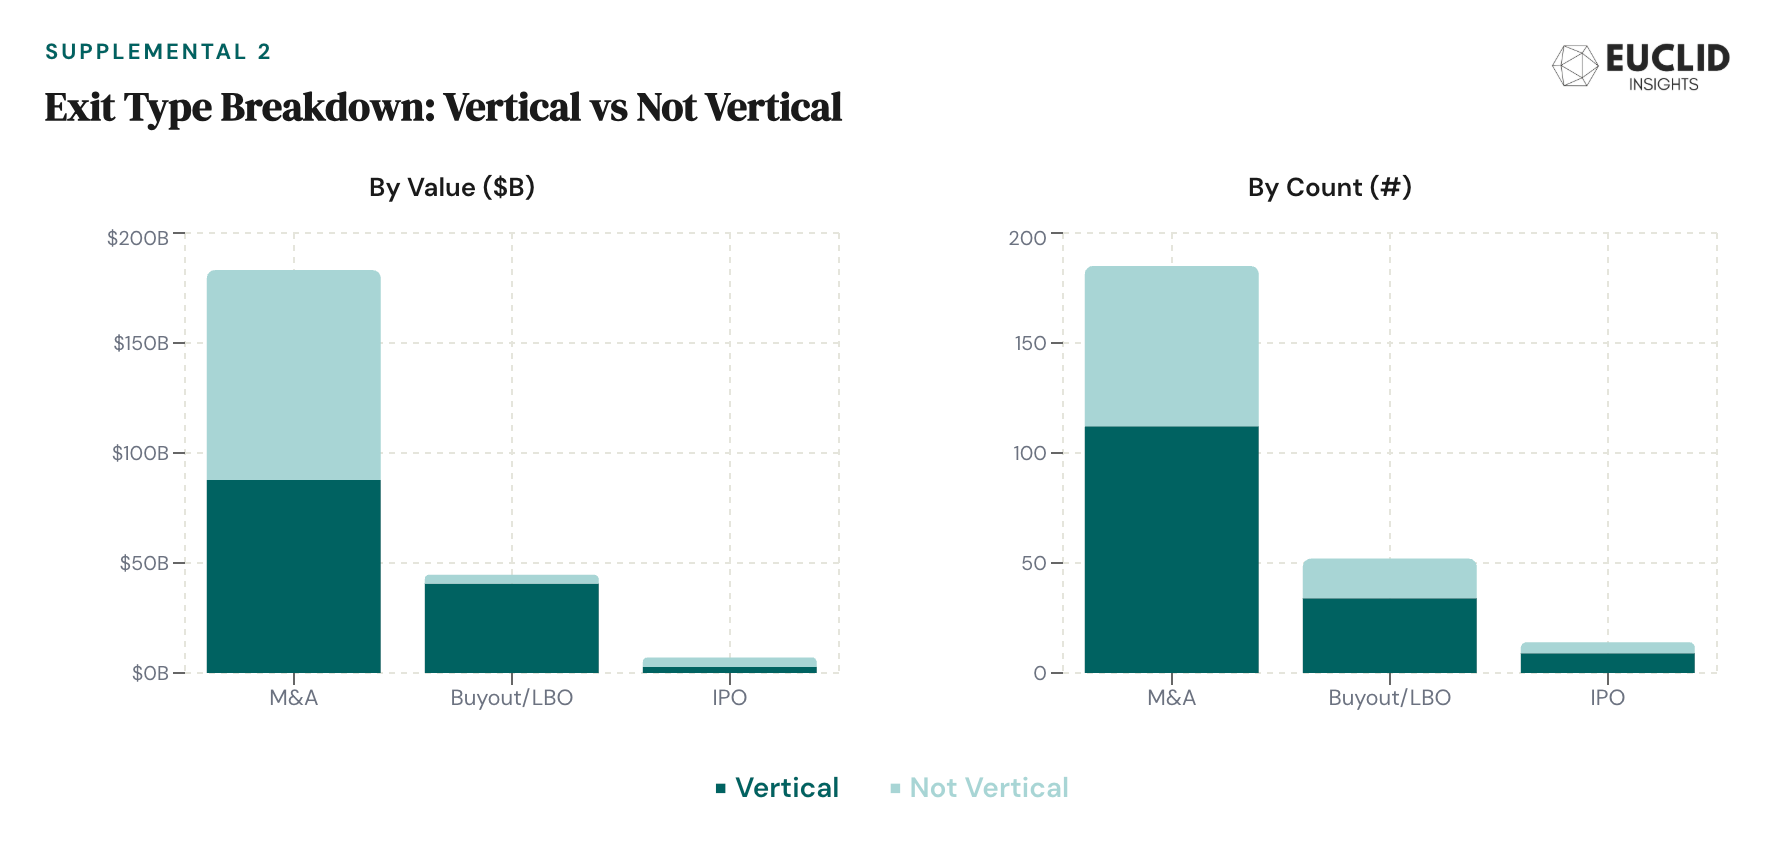
On the exit side, 2025 delivered $131.1B across 158 vertical exits—a number skewed at the top by Ansys and a handful of mega-buyouts, but broad at the base: Healthcare alone generated 43 exits worth $17.1B, and the IPO window cracked open with 18 vertical offerings including Via and Hinge Health. Including horizontal deals, 2025 exits totaled $234.9B across 254 transactions—vertical companies captured 56% of total exit value. Excluding Ansys (the $35B acquisition that threw all the numbers off), vertical liquidity was almost exactly on par with non-vertical.
This report examines 2025 in full: deal volume and capital deployment trends, vertical-by-vertical breakdowns, stage dynamics, top investors, and geographic concentration—plus profiles of twenty thematically notable vertical deals to know. We conclude this report with Euclid’s perspective on the undercurrents and structural shifts we believe will define Vertical AI in the year to come.
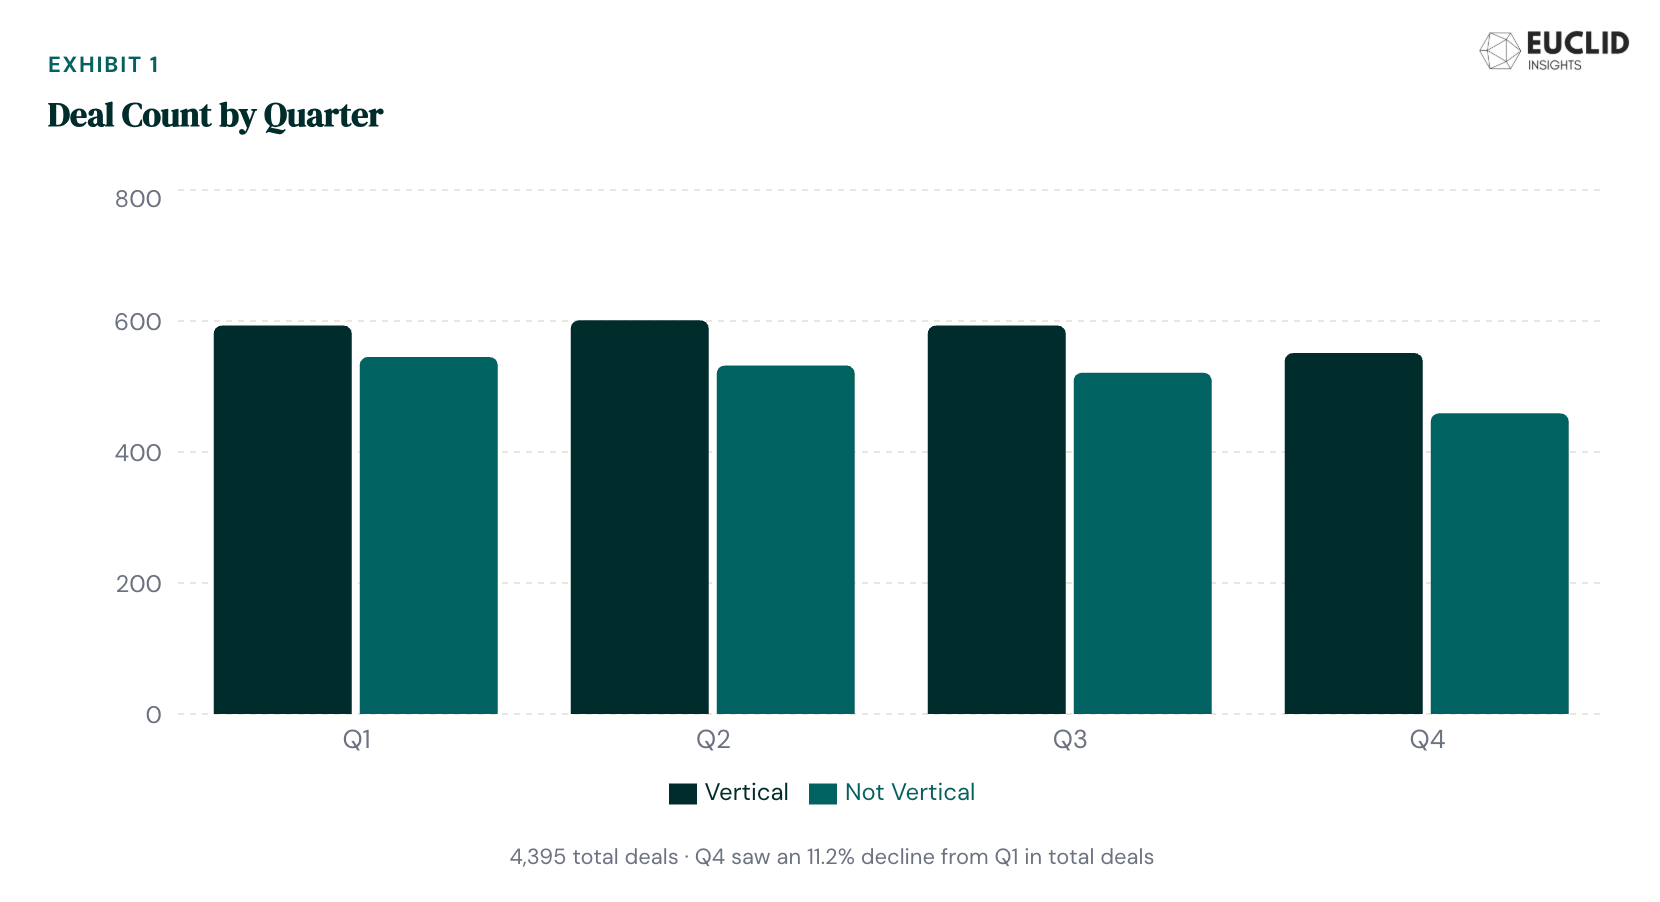
The US and Canadian VC market produced 4,395 software and AI financing deals of $1M+ in 2025 (excluding non-relevant deals), deploying $186B in aggregate capital. Deal volume across quarters was relatively even: Q1 and Q2 combined for 2,271 deals (52% of the year), while Q4 saw a cooldown to 1,010 deals—the lightest quarter and an 11% decline from Q1.
Capital deployment told a different story. Q1’s $60.5B was inflated by OpenAI’s $40B Series F—strip that out and Q1 looks closer to $20B, making the quarterly trajectory even more—a pattern consistent with our thesis on vertical AI market sizing. Vertical companies captured 19% of Q1 capital, then surged to 34% in Q2 as non-vertical mega-rounds dried up, before settling at 32% in Q3 and climbing to 42% in Q4. The full-year split—$56.2B vertical versus $129.8B non-vertical—still understates the vertical story thanks to a small handful of foundation model and infrastructure rounds (OpenAI, Anthropic, GPU cloud companies) in the non-vertical capital pool. On a per-transaction basis, verticals averaged $24.0M in deal size versus $63.1M for non-verticals, reflecting the latter’s concentration in capital-intensive model training and infrastructure.
To read the full piece, head over to The Verticalist on Substack.